Insurance not paying enough for your Laredo property damage?
Commercial property is a major focus of our work. We have helped more than 2,000 clients in Laredo, including many commercial property owners. We also assist homeowners.
Free initial inspection and claim review. Assistance in English and Spanish. If the information supports the insurer’s payment, we will tell you at no cost.
Your contacts for Laredo warehouse and commercial claims
Martha Guerra
Public Adjuster · Bilingual client and claims support
Martha speaks fluent Spanish and has worked with the Laredo community since 2014. She understands the area’s warehouse, industrial, shipping and freight businesses. She works closely with clients and insurance companies, helping explain claim details and keeping communication clear throughout the process.
Cord Largo
Senior Public Adjuster & CEO
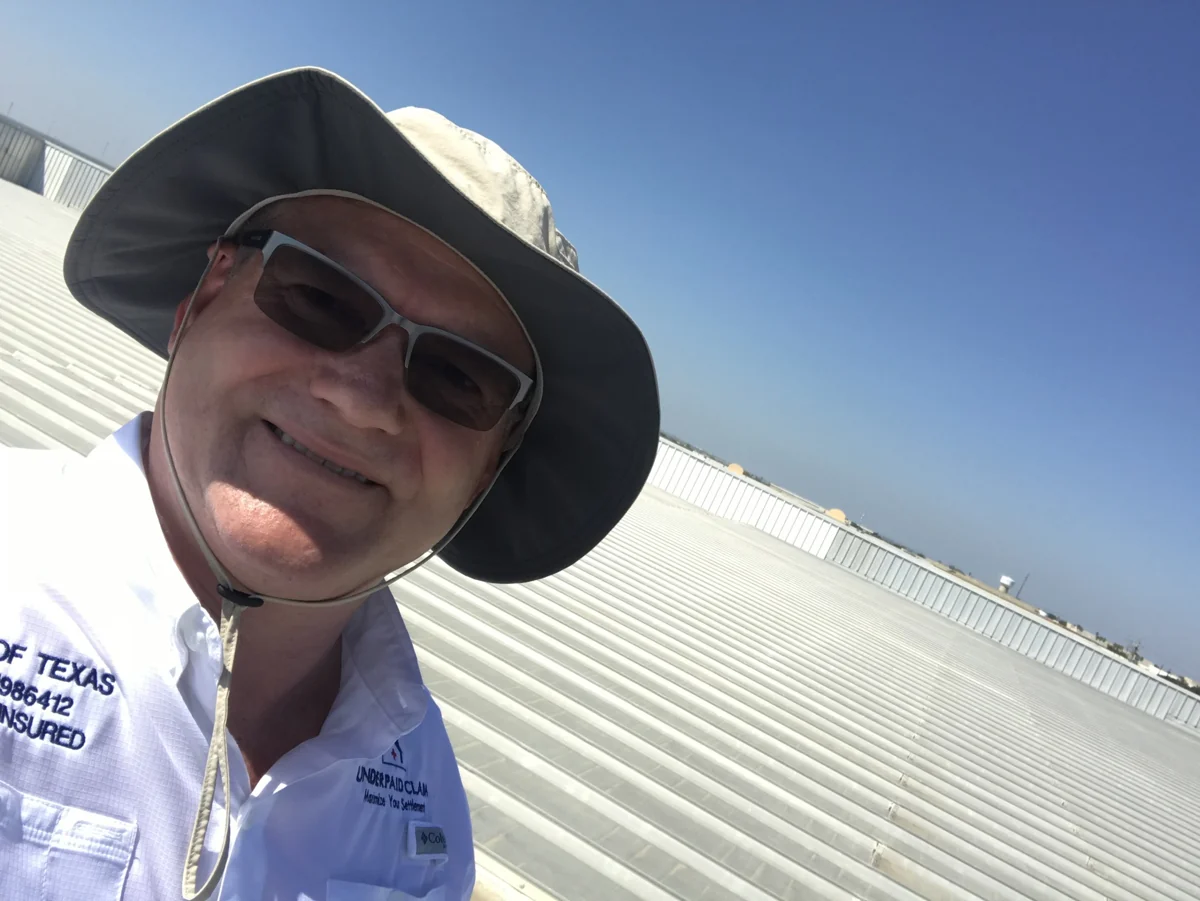
Cord personally participates in every Laredo case. He handles inspections, verifies and documents the damage, and oversees the preparation of the supported repair estimate. For large warehouse and commercial claims, that means direct involvement from the senior adjuster responsible for evaluating the loss.
Cord Largo on site in Laredo · Inspection photograph, August 28, 2018.
Personal involvement, from inspection to representation
Together, Martha and Cord provide personal support and representation for Laredo property owners, with assistance available in English and Spanish.
Our work in Laredo began in 2014, helping commercial warehouse owners and residents following a major storm. We have continued serving the community for many years. Local public adjusters support our Laredo clients, with additional experts brought in as needed.
Commercial insurance claim help in Laredo
A payment that does not appear to cover the repairs can leave a property owner unsure what to do next. Bring us the concern: a roof repair allowance, water damage missing from an estimate, fire damage, a denial or a delayed response.
We begin with the property and the available evidence. We inspect the relevant damage, take photographs and measurements, identify materials and prepare a supported repair estimate using Xactimate, an industry-standard estimating platform. The claim must account for the actual property and documented damage; the difference between two estimate totals is not automatically money owed.
Keep each affected area identifiable
For a commercial property, organize the records by building, unit or affected area. Identify the owner or authorized contact, access arrangements, and any cleanup or protective work already performed. Keep the insurer’s estimates, payment letters, photographs and contractor records together.
We develop our own documented estimate from the actual damage. Your contractor can explain construction details; as your licensed public adjuster, we represent you in negotiating the supported claim. Understand estimate differences and the contractor’s role.
The water cleanup is done, but repairs are missing.
Keep the cleanup invoice, photographs and any drying records. We review remaining damage and work already included or paid so the claim does not request payment twice for the same work. Review repairs after water cleanup.
What if the property has fire or smoke damage?
Save photographs, emergency-work invoices and records identifying affected rooms and materials. Tell us what has been removed or cleaned so we can assess what evidence is still available. Explore fire and smoke claim help.
Can you review a denied or delayed Laredo claim?
Share the written decision, claim timeline and available damage records. We can review the concern and explain whether public adjusting fits your situation. Coverage and deadlines depend on the policy and facts. See denial and delay next steps.
How your Laredo claim review works
Tell us about the property. Share Laredo as the city, the property type and your claim concern. You do not need to upload private documents through the initial form.
Review the available records. We are happy to review the insurer’s documents before traveling. Sometimes they identify an omission or inconsistency without an initial site visit.
Inspect when needed. We normally meet at the damaged property. Visits are typically arranged within a day or a few days; major disasters, demand and access can affect timing.
Document and present the supported claim. When you retain us, we submit the estimate and supporting evidence and discuss the findings with the insurer. A reinspection may be appropriate.
English and Spanish assistance for Laredo property owners
Our team speaks Spanish. We can help with initial questions, inspection arrangements and claim discussions in either language. We serve Laredo and all of Texas; this page describes a service area, not a separate Laredo office.
Free inspection and honest claim review
We do not assume every claim is underpaid. If the available information supports the insurance company’s payment, we will explain that finding at no cost. If we identify a documented concern, we explain what work may be needed next.
If you retain us, our fee is 10% of new money received, with no fee on prior payments and no additional expenses. If no new money is received, no fee is due. Representation begins through a written agreement.
These photographs from our inspection archive show roof details, building interiors and rooftop equipment. Dates identify the capture dates recorded in the files, not storm dates. The images illustrate observed conditions; photographs alone do not determine cause or coverage.
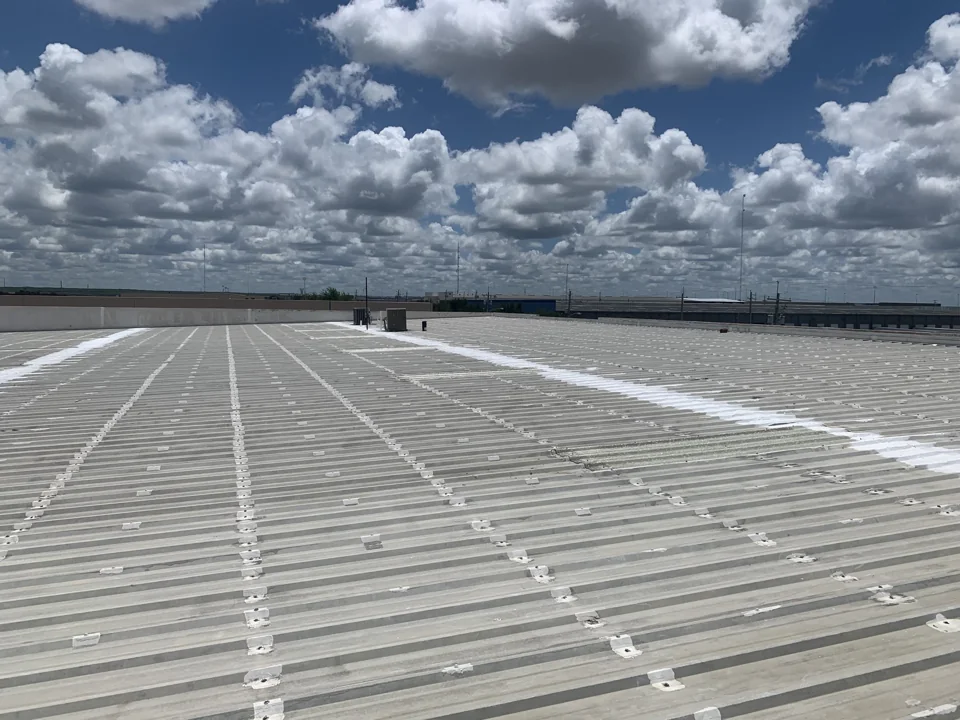
Start with the whole roof
A wide inspection view records the metal panels, rows of fasteners, rooftop equipment and areas of white coating. It gives context for the close-up observations.
Laredo · Inspection photograph · 2020-06-03
Examine fasteners and surrounding materials
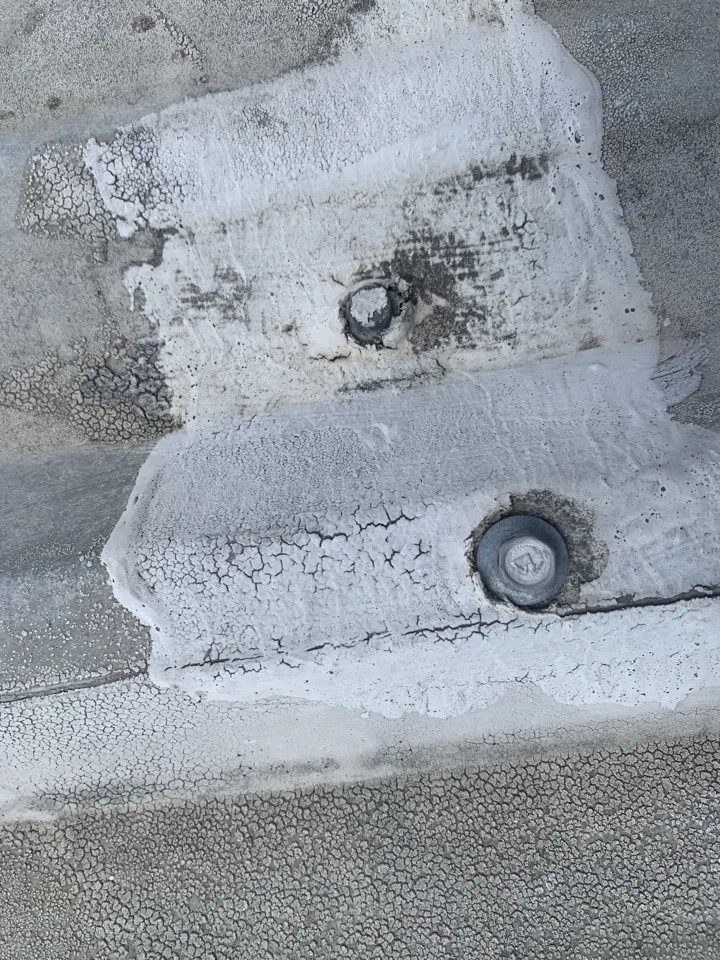
This close-up shows exposed fasteners and cracking in the white material around them and along a panel joint. We record the condition of each component rather than treating the roof as a single surface.
Laredo · Inspection photograph · 2020-06-03
Include roof-light panels and their edges
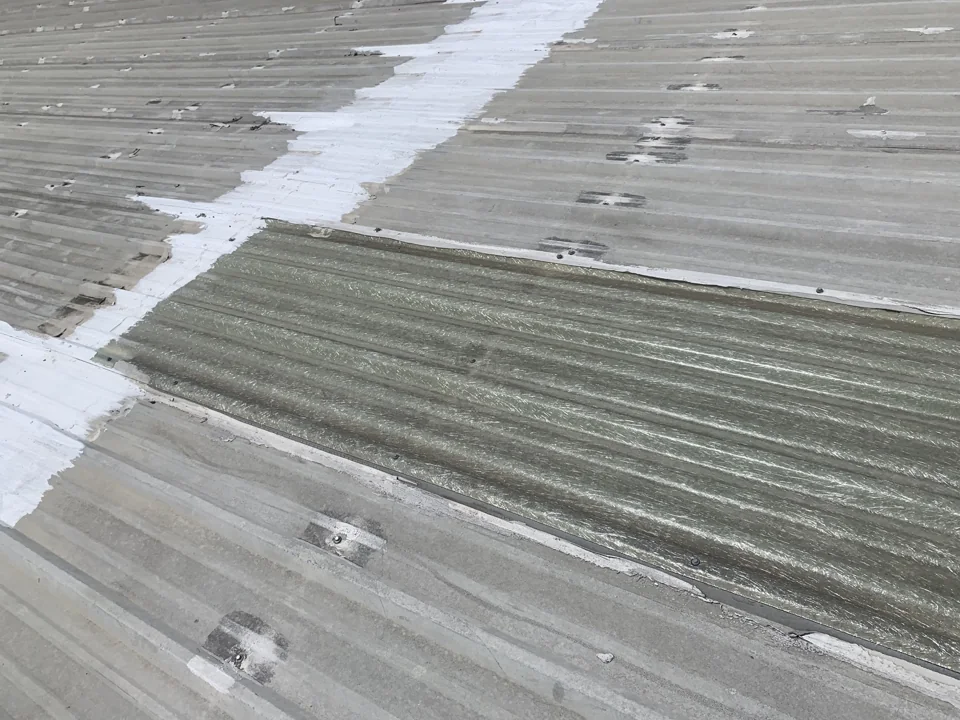
A translucent roof panel sits within the metal roof. The photograph records its edges, fasteners and surrounding sealant or coating as part of the inspection.
Laredo · Inspection photograph · 2020-06-03
Look below the roof as well
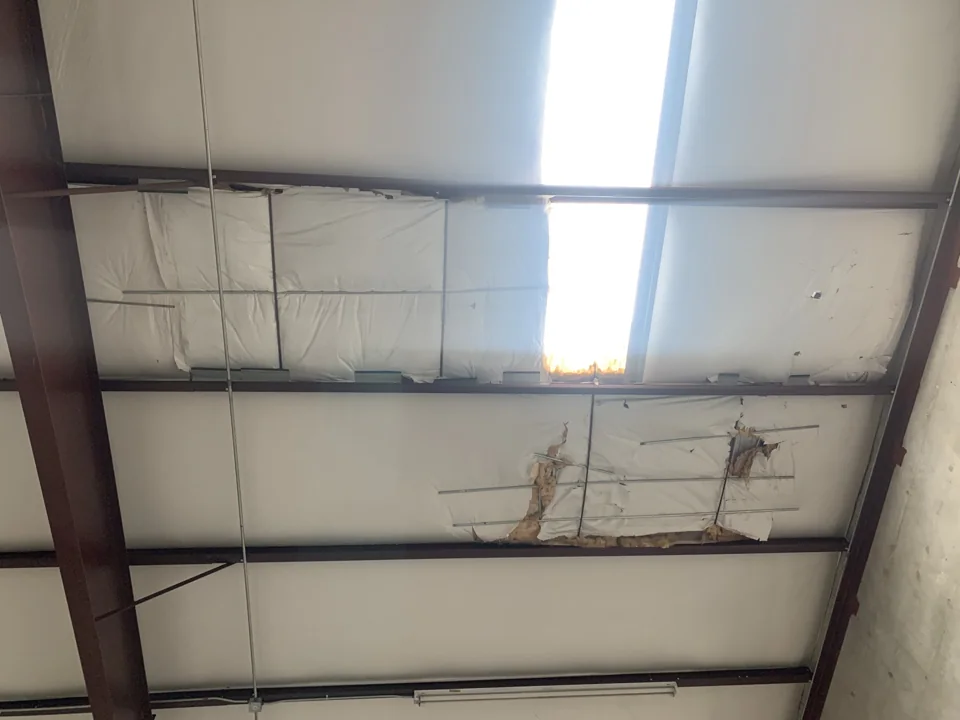
The interior view shows tears and openings in the insulation facing, with insulation exposed in several areas. Interior observations help identify locations that need closer examination above.
Laredo · Inspection photograph · 2020-06-03
Document connections from below
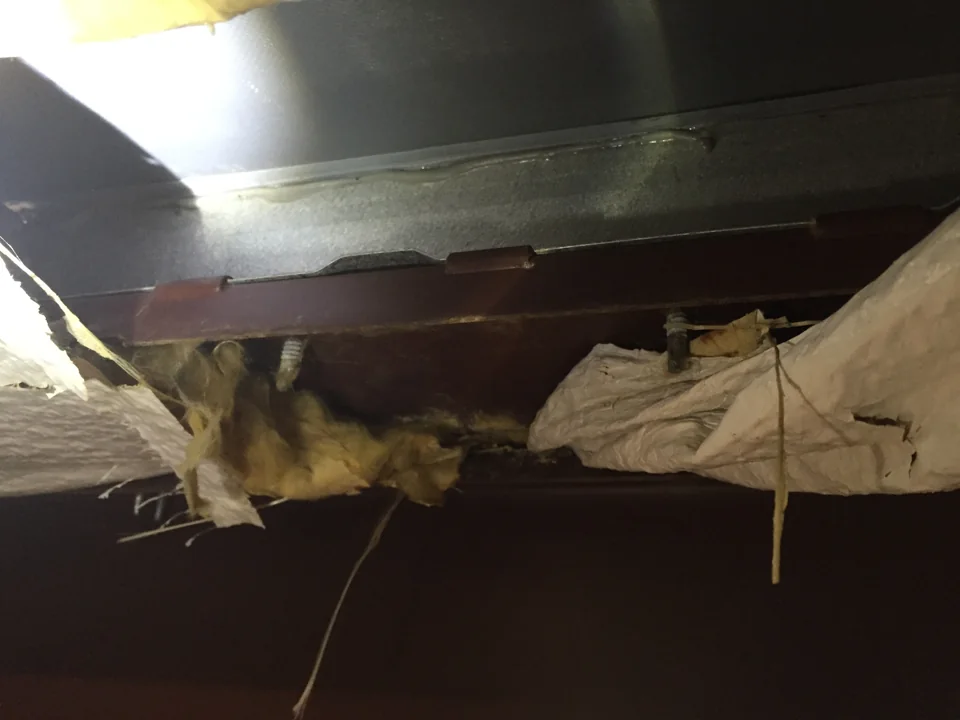
An underside view records metal framing, projecting fasteners and exposed insulation. Close-up documentation preserves details that a rooftop overview cannot show.
Laredo · Inspection photograph · 2015-01-27
Inspect rooftop equipment too
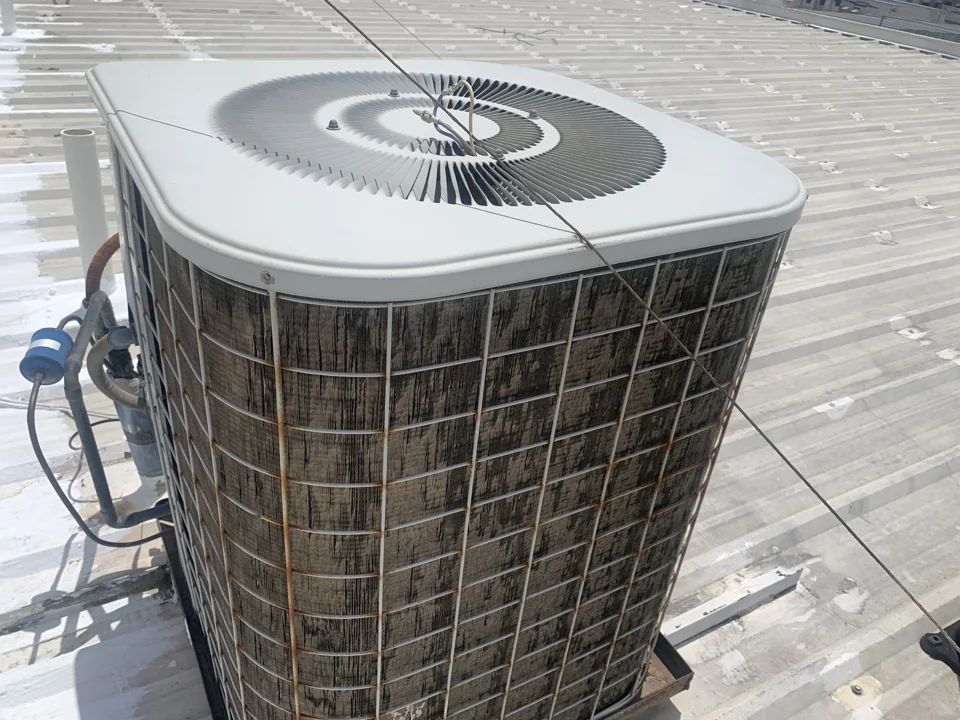
This rooftop air-conditioning unit has visibly distorted coil fins. We document equipment condition separately from the roof covering; the cause and repair needs require the full inspection record.
Laredo · Inspection photograph · 2020-06-03
Does a roof warranty cover wind or hail damage?
A manufacturer’s roof warranty and a property insurance policy are different agreements. A storm-related repair may fall outside a manufacturer’s warranty. That does not automatically void the entire warranty, prove storm damage, or establish that an insurer owes for replacement. The issued warranty, any riders, the insurance policy and the documented damage must be reviewed separately.
What roofing manufacturers actually say
GAF TPO/PVC: GAF’s induction-welded system manual states, “GAF’s guarantees do not provide coverage for hail.” The same guidance explains that hail coverage can be purchased for selected systems with advance written approval. It describes a standard wind-leak limit of 55 mph and enhanced options for qualifying systems. Read GAF’s Guarantee Guidelines, GG-3, notes 3 and 5 (PDF page 8).
Englert metal/membrane roofs: Its specimen 20-year Single Source/NDL weathertightness warranty excludes leaks caused wholly or partly by specified natural events, including hail and windstorms exceeding a 72-mph three-second gust, measured as the document specifies. The issued warranty and riders must be checked. Read Englert’s exclusions, item 5 (PDF page 2).
Coverage can differ: Carlisle advertises warranty options that can include hail up to three inches and winds up to 120 mph. Those are available options, not coverage promised for every roof. Read Carlisle’s warranty overview.
Is metal-roof damage only cosmetic?
A manufacturer’s warranty exclusion is not an insurance cosmetic-damage exclusion. TDI explains that some home policies exclude damage affecting a metal roof’s appearance while it still functions. Read TDI’s metal-roof insurance guidance.
TDI’s historical residential forms HO-145 and TDP-022 distinguish appearance changes from hail damage allowing water penetration or impairing the roof’s ability to keep out the elements over time. These are specific residential forms, not a universal definition for commercial warehouse policies. Read TDI Bulletin B-0030-98 and its endorsement language.
For a leaking warehouse roof, we examine the applicable endorsement and evidence of damage to seams, connections, membranes and other relevant components. Neither a dent nor a leak alone establishes the cause or coverage. We document why the observed condition matters to the proposed repair.
What to provide for a review
Keep the issued roof warranty and riders, roof specifications, maintenance and repair records, insurance policy and endorsements, the insurer’s written explanation, and available photographs and leak history. Manufacturer notice deadlines and repair-approval requirements may apply; check the actual warranty promptly.