Published by Under Paid Claim LLC. Meet our public adjusters and check their licenses.
Reviewed by Cord Largo · Texas license #1862708 ·
Make the fire and smoke claim file understandable
After a fire, records may describe building damage, smoke or soot observations, emergency work and damaged belongings. Different people may hold the photographs, estimates and invoices. Organizing those records helps identify which part of the insurer’s estimate or payment concerns you.
Under Paid Claim LLC helps homeowners and commercial property owners in McAllen, Mission, Edinburg and the Rio Grande Valley review property claim documentation. We inspect relevant accessible conditions, prepare supported estimates when retained and present the claim information to the insurance company.
What to keep together
- Available photographs of affected rooms, surfaces and materials before and during emergency work.
- The insurer’s latest estimate, payment letters and any written coverage explanation.
- Cleaning, mitigation and repair proposals with their dates and locations.
- Relevant professional reports and a separately identified contents inventory where applicable.
- A timeline showing inspections, work performed and communications.
Do not enter a damaged building until the responsible qualified parties say access is safe. Do not handle hazardous materials or postpone necessary protective work while waiting for our visit. Explain what changed so earlier records can be connected with conditions that remain visible.
Inspect the scope, then reconcile the payment
A fire-loss check can differ from a repair estimate because of policy terms, deductions, prior payments or the stage of the claim. Identify the affected material and proposed repair separately from the payment calculation. Our payment guide explains the distinction.
We provide public adjusting. Restoration, engineering and specialized testing are carried out by separately qualified providers. An attorney handles legal advice and representation where needed. Our review does not extend policy or legal deadlines.
A fictional example of organizing observations
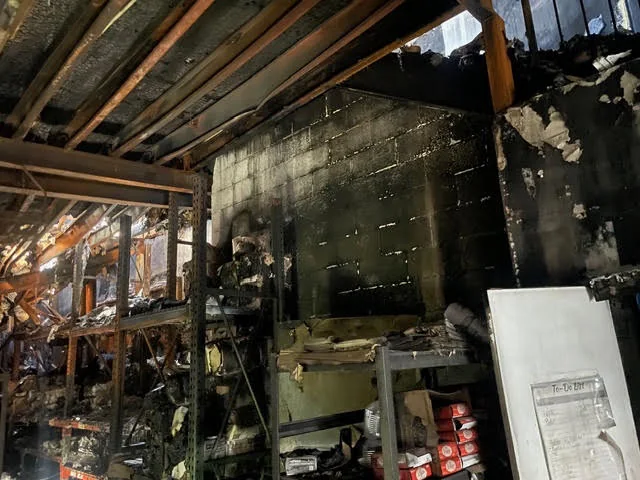
Suppose a room near the fire has visible damage and a second room has documented smoke residue. The file should identify the observations and proposed work for each room, together with relevant professional findings. Whether particular work belongs in the covered loss depends on the evidence and policy. This example is fictional and does not describe a client result.
For a business property, see our commercial claim review. For a home, see residential claim help. Our inspection guide explains how we connect observations and records.
Questions about fire and smoke claims
What can you review when smoke reached rooms away from the fire?
We can review relevant accessible conditions, photographs and records describing smoke, soot and affected materials. A condition in another room needs documentation; the extent of the claim cannot be decided from the distance to the fire alone. Specialized testing or remediation may require a separate provider.
What records help if emergency cleaning happened before your visit?
Keep photographs taken before and during cleaning, the contractor’s scope, invoices, reports and the dates of work. Explain which areas or items changed. Do not delay necessary safety or protective work to preserve an inspection opportunity.
How should I organize a list of damaged belongings?
Keep an inventory identifying the item, location, available photographs and supporting purchase or replacement information. Distinguish damaged property from repair work on the building. Discuss a secure way to share records; the initial website inquiry does not require an inventory upload.
Can you review a partial fire-loss payment?
Yes. Bring the insurer’s estimate, payment letters and the remaining areas of concern. A payment may address only part of a file or reflect deductions and policy conditions. We review the damage scope and reconcile the payment separately.
Do you provide engineering, testing or fire restoration?
Our service is public adjusting. Repairs, engineering, specialized testing and remediation are separate services performed by appropriately qualified providers. We can explain which records would be relevant to the adjusting concern without presenting their work as our own.
What if I disagree with the insurer’s fire or smoke estimate?
Identify the specific material, quantity or work item in dispute and keep the supporting records. A documented estimate comparison may clarify the issue. A disagreement about coverage or legal rights may require an attorney. Review our professional roles guide.
Start with a free inspection and claim review
Our initial property inspection and claim review are free. If the records and inspection support the insurer’s payment, we will explain that finding at no cost to you. We do not assume every claim is underpaid.
Request a free claim review or call 956-772-4404. Tell us the property city or ZIP code and the concern. Assistance is available in English and Spanish.
If you retain us, our fee is 10% of new money received, with no fee on payments received before you hire us and no additional expenses. If no new money is received, no fee is due. Representation begins through a written agreement.