Understand the repair gap.
The insurer’s estimate and a repair quote may include different work, quantities or pricing. Payment can also reflect deductibles, depreciation and policy limits. Those differences need to be understood separately.
Keep the claim records together.
For accepted claims, we review relevant policy records, document property damage and prepare a supported claim position to present to the insurer.
Three terms that affect the payment
- Deductible: The portion of a covered loss that remains your responsibility under the policy.
- Depreciation: A deduction for age or wear; whether an amount may be recoverable depends on the policy.
- Coverage limit: The maximum payable for a particular coverage, subject to the policy’s terms.
Documents that may help
- Your policy and declarations page.
- The insurer’s estimate and payment information.
- Written decisions and explanations of deductions.
- Photographs, repair estimates and relevant invoices.
- A short timeline of important claim communications.
You do not need to upload these to start an inquiry. Tell us what is available, and we can discuss what is needed next.
Decide whether representation fits.
Discuss the proposed service, fee calculation and claim circumstances before signing an agreement. We do not repair the property or provide legal representation.
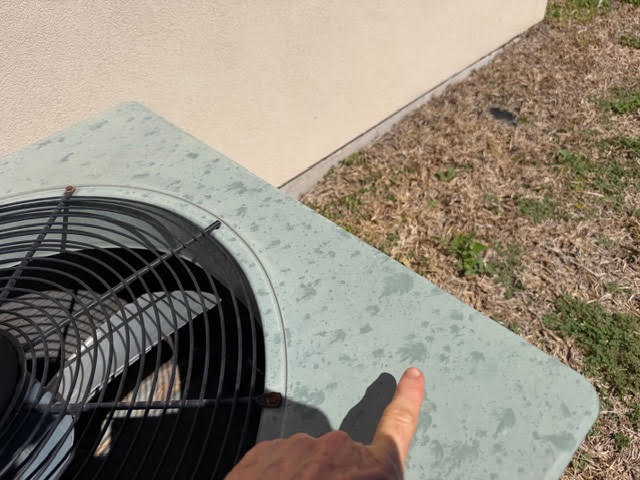
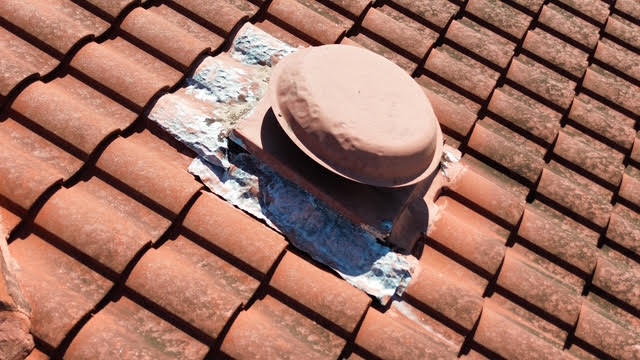
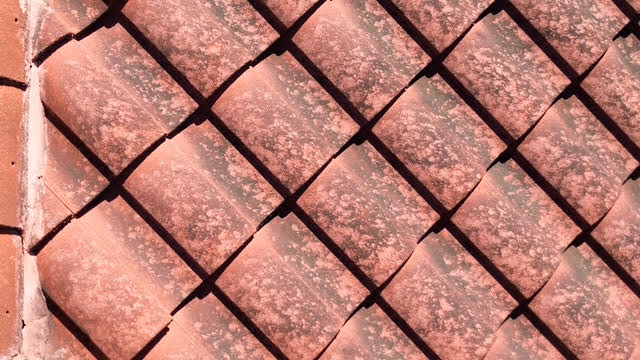
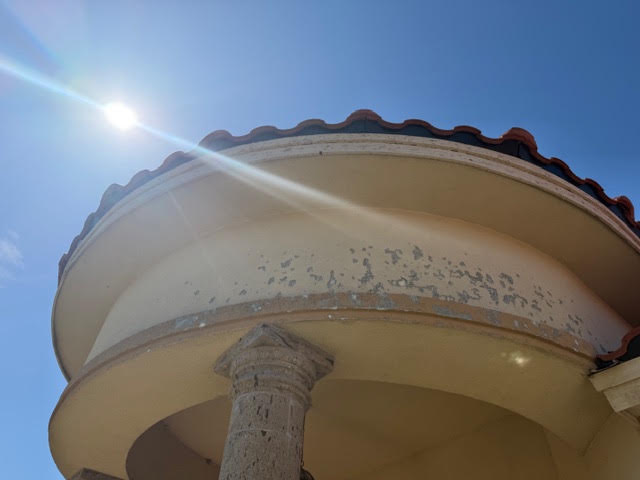
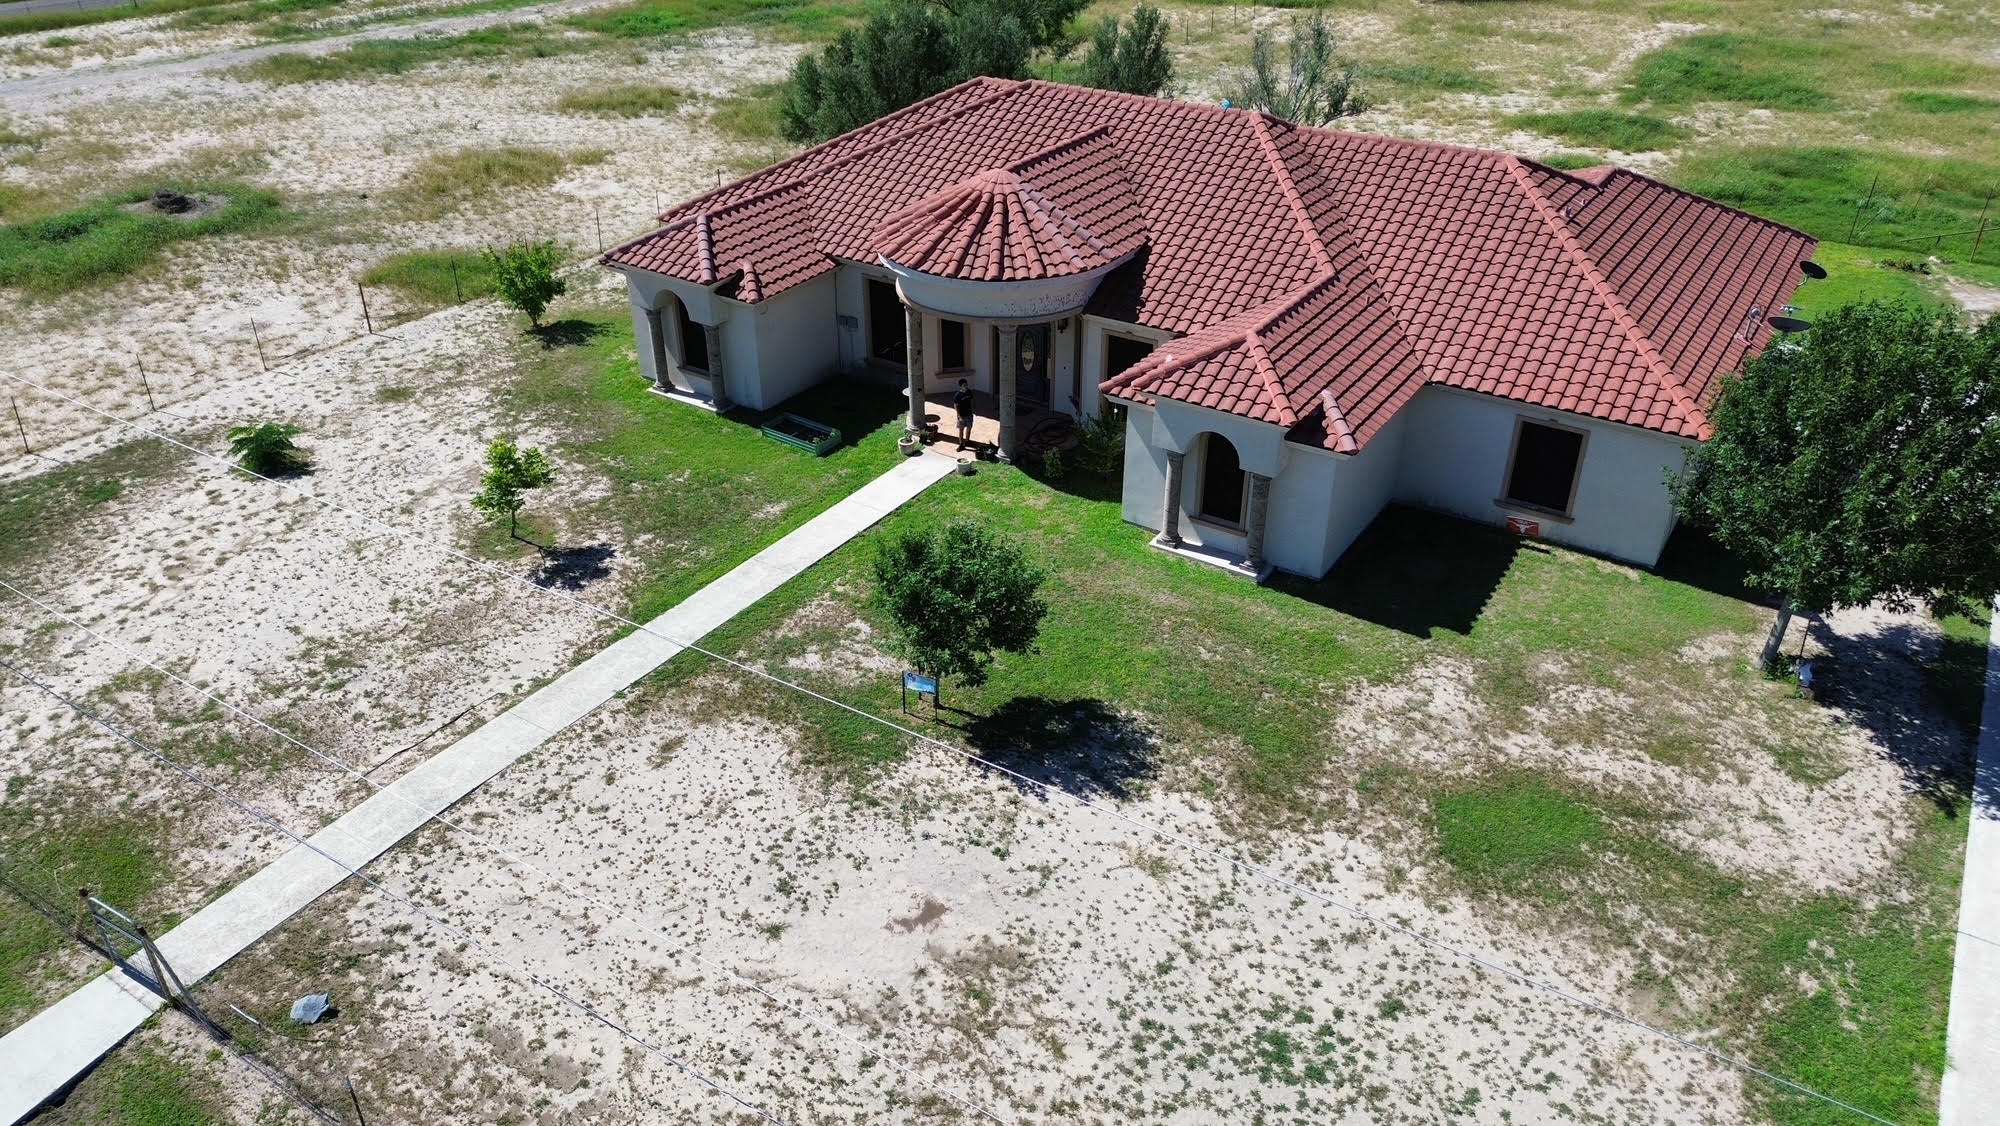
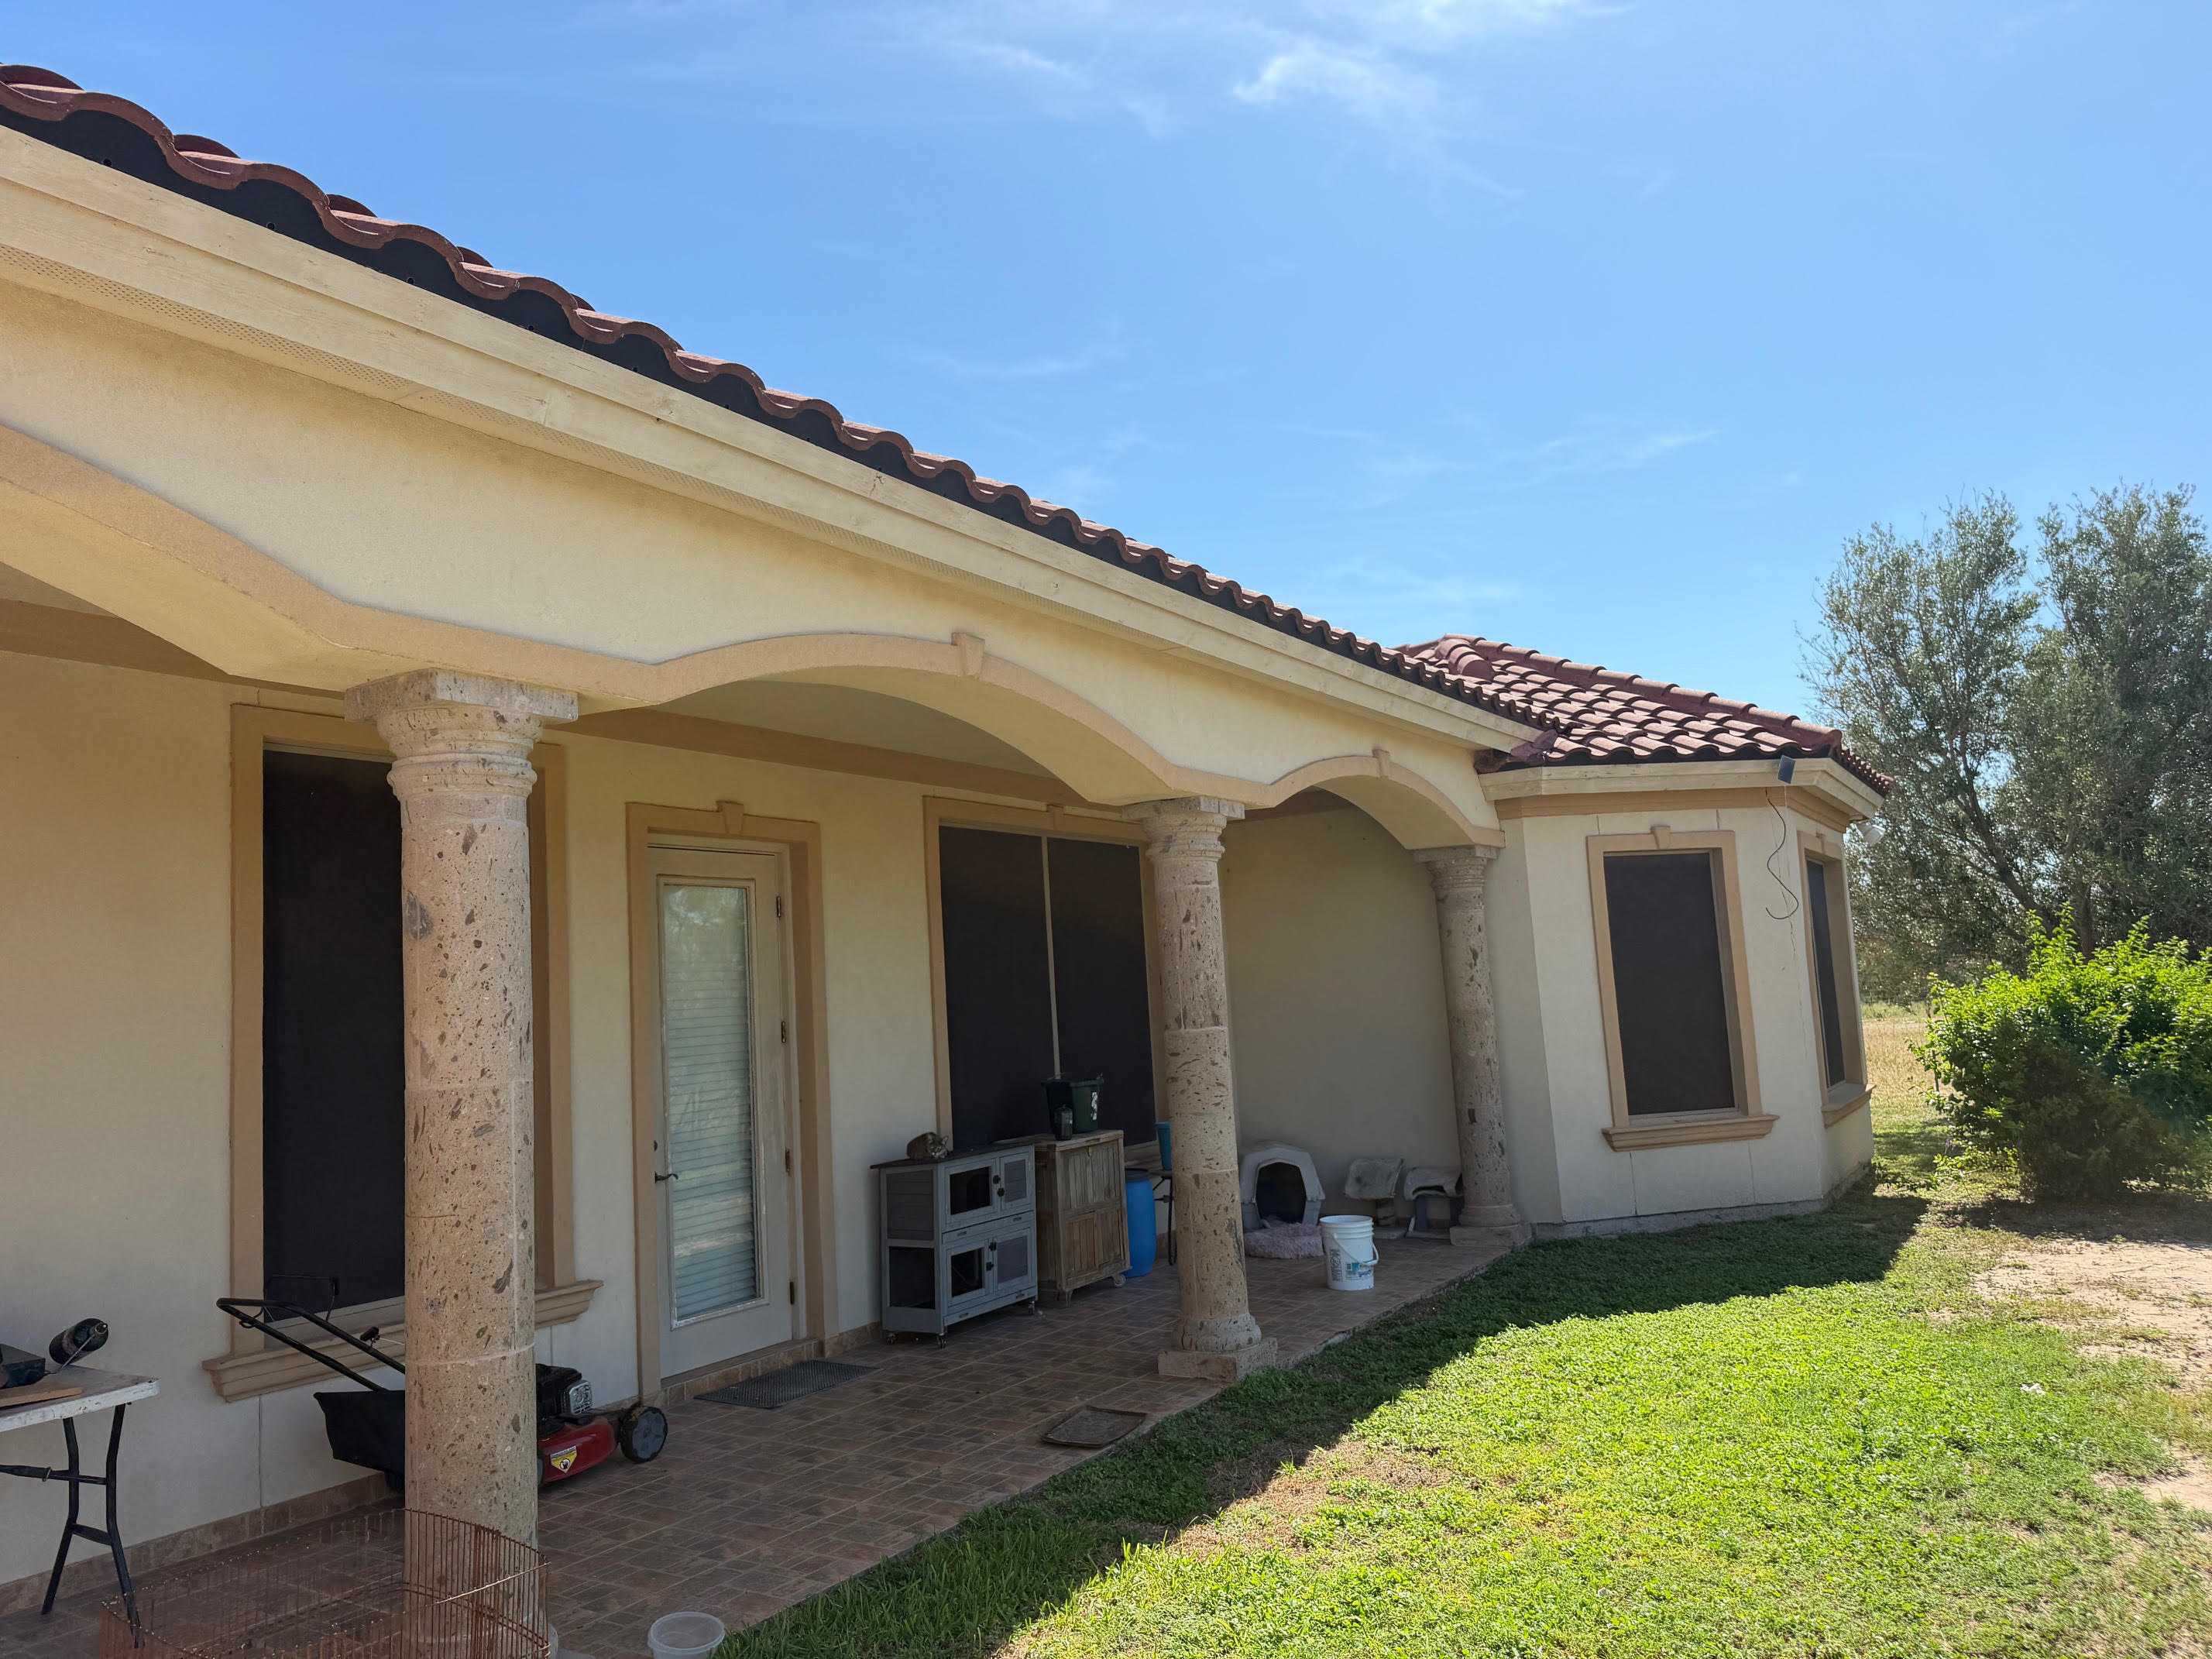
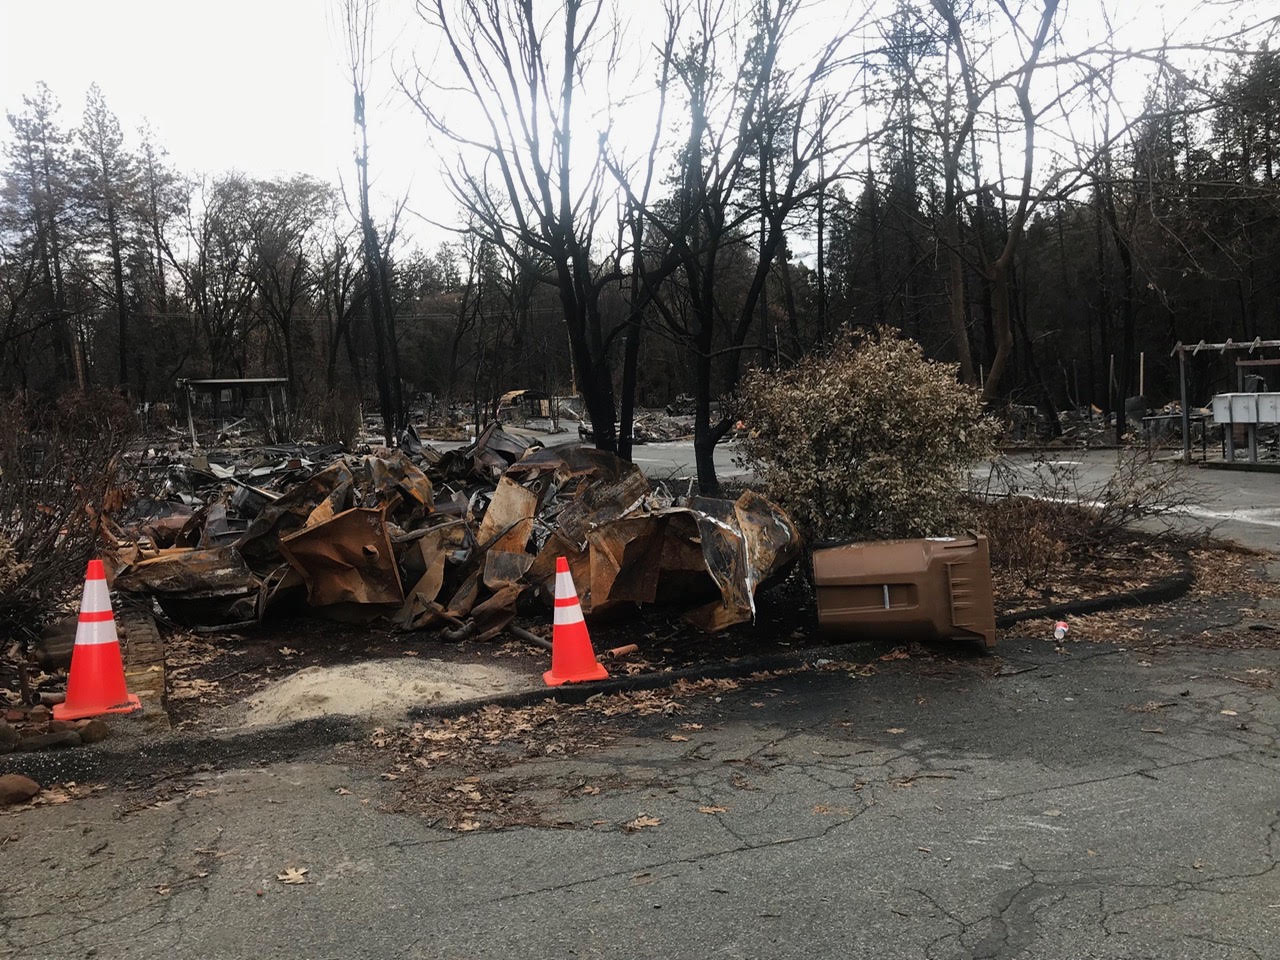
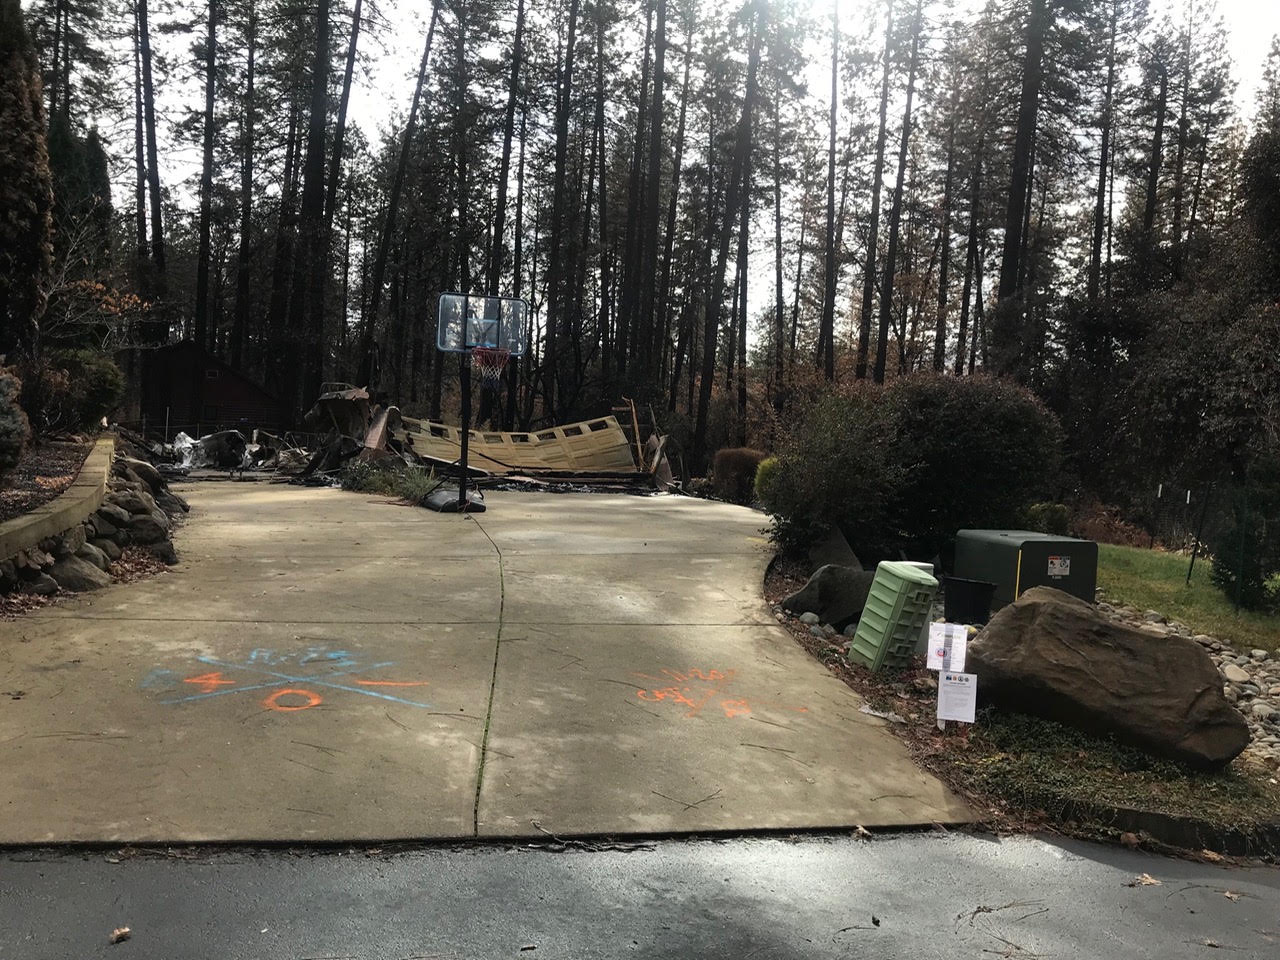
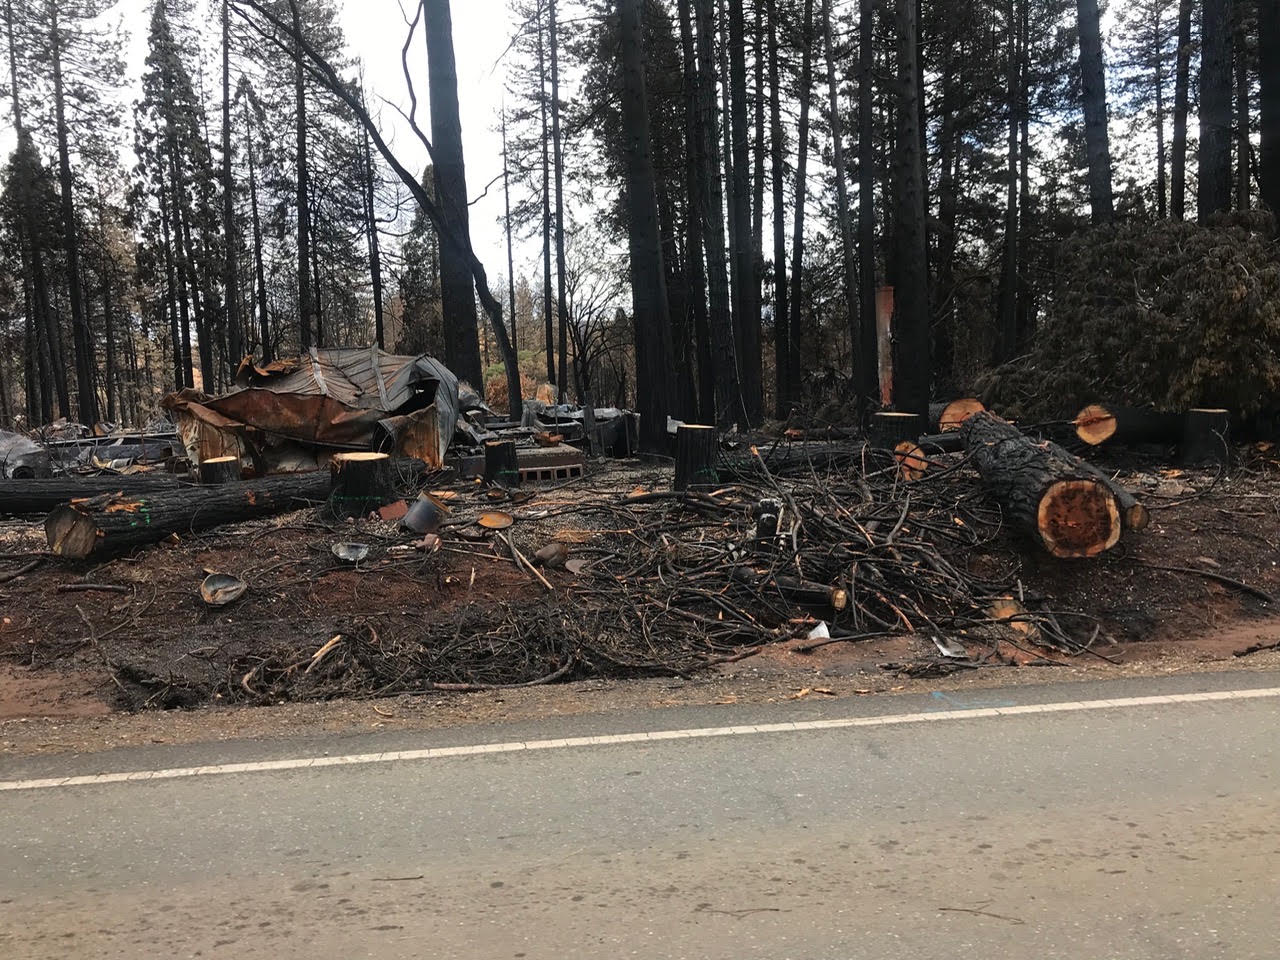
Residential damage and inspection photos
Photographs from the field show why careful property documentation matters.